


Key Takeaways
- UPI 2.0 rolled out with intent‑based payments and a target of 10 billion monthly transactions by FY27.
- RBI expanded the e₹ pilot to 15 additional banks, covering retail and wholesale use cases.
- JioPay launched a UPI‑linked wallet with instant cashback on utility bill payments.
- Flipkart introduced a split‑pay feature allowing users to divide a purchase across up to three UPI IDs.
- Several NBFCs unveiled AI‑driven credit scoring models that use alternative data such as utility and telecom payments.
What's the news
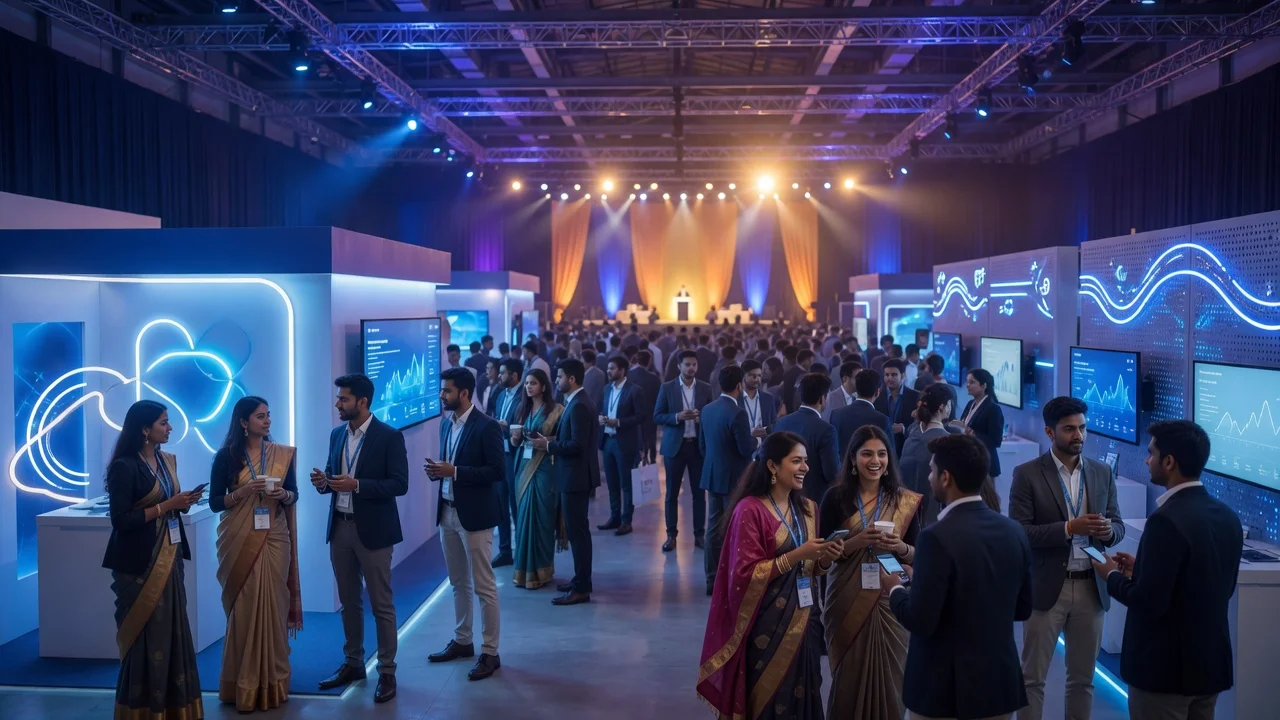
The Global Fintech Festival 2026 opened in Mumbai with a packed agenda of product demos, policy talks and startup pitches. The first day was dominated by launches that aimed to deepen the reach of digital payments and expand the scope of India’s central bank digital currency (CBDC). Organisers said the focus this year was on making fintech solutions more inclusive and interoperable.
Details
UPI 2.0, the latest iteration of the Unified Payments Interface, was unveiled by NPCI. The upgrade adds intent‑based payment flows, allowing users to pre‑authorise transactions for subscriptions or recurring bills without entering a UPI PIN each time. NPCI also announced a new transaction ceiling of ₹2 lakhs per peer‑to‑peer transfer for verified merchants, aiming to support higher‑value commerce.
On the CBDC front, the Reserve Bank of India shared that the e₹ pilot now includes 15 more banks, taking the total participating entities to 30. The expanded trial covers both retail consumers and wholesale segments, with a particular focus on cross‑border remittances using the e₹‑RMB bridge. RBI officials highlighted that transaction latency has dropped to under two seconds in the latest test runs.
JioPay, the payments arm of Reliance Jio, introduced a wallet that sits on top of UPI. Users can load money via bank transfer or debit card and then pay merchants using the familiar UPI QR. The wallet offers an instant 5 % cashback on electricity, water and gas bill payments, capped at ₹100 per month. Jio said the goal is to drive wallet adoption among users who prefer a prepaid‑style experience.
Flipkart’s new split‑pay feature lets shoppers divide a single order across up to three different UPI IDs at checkout. The move targets group purchases, such as shared electronics or household goods, and aims to reduce cart abandonment caused by payment limits on individual accounts. Flipkart said early internal tests showed a 12 % increase in conversion for orders above ₹5 000.
Several NBFCs, including a prominent player in the micro‑loan space, showcased AI‑driven credit scoring models that incorporate alternative data streams like mobile recharge patterns, utility bill payments and even social media activity (with user consent). The models claim to improve approval rates for thin‑file borrowers by up to 18 % while keeping non‑performing assets below 1 %.
India impact
The announcements collectively push India’s digital payments ecosystem toward higher transaction values, broader user segments and more seamless experiences. UPI 2.0’s intent‑based flow could reduce friction for subscription services, benefiting SaaS firms and content platforms. The expanded e₹ pilot signals the RBI’s commitment to testing a retail CBDC at scale, which could eventually lower reliance on cash for small‑value transactions.
JioPay’s wallet may attract users who are wary of linking their primary bank account directly to UPI, especially in semi‑urban areas where prepaid habits remain strong. Flipkart’s split‑pay addresses a real pain point for group buying, potentially boosting average order values on e‑commerce platforms.
The alternative‑data credit models could expand formal credit access to millions of Indians who lack traditional credit histories. If scaled responsibly, this could stimulate consumption in sectors like consumer durables and education.
Use cases
Imagine a family planning a monthly grocery bill. With UPI 2.0, they can set a recurring intent to pay the local kirana store via QR, and the amount gets deducted automatically on the chosen date without entering a PIN each time. For a college student sharing a rented apartment, Flipkart’s split‑pay lets three roommates pay their share of a furniture purchase using their own UPI IDs, avoiding the hassle of collecting money first.
A small merchant in Jaipur can accept JioPay wallet payments from customers who prefer to preload a fixed amount each week, reducing the risk of failed transactions due to insufficient bank balances. Meanwhile, a farmer in Maharashtra seeking a short‑term loan for seeds can now get approved based on his regular mobile recharge and electricity bill payment history, thanks to the new AI scoring model.
Honest take
Day one of GFF 2026 showed that the Indian fintech scene is moving beyond basic P2P transfers and entering a phase of layered functionality. The upgrades are practical, targeting real‑world friction points rather than chasing hype. However, the success of these launches will depend on adoption rates, user education and the ability of banks and NBFCs to integrate the new APIs without creating fragmentation.
While the e₹ pilot expansion is encouraging, questions remain about privacy, offline functionality and how the digital rupee will coexist with existing UPI infrastructure. The alternative‑data credit models, though promising, need clear governance to prevent misuse of personal information. Overall, the tone set on day one is optimistic but cautious – a sign that the industry recognises both the opportunity and the responsibility that comes with scaling financial innovation in a diverse market like India.




Comments (0)
Be the first to comment!