


Key Takeaways
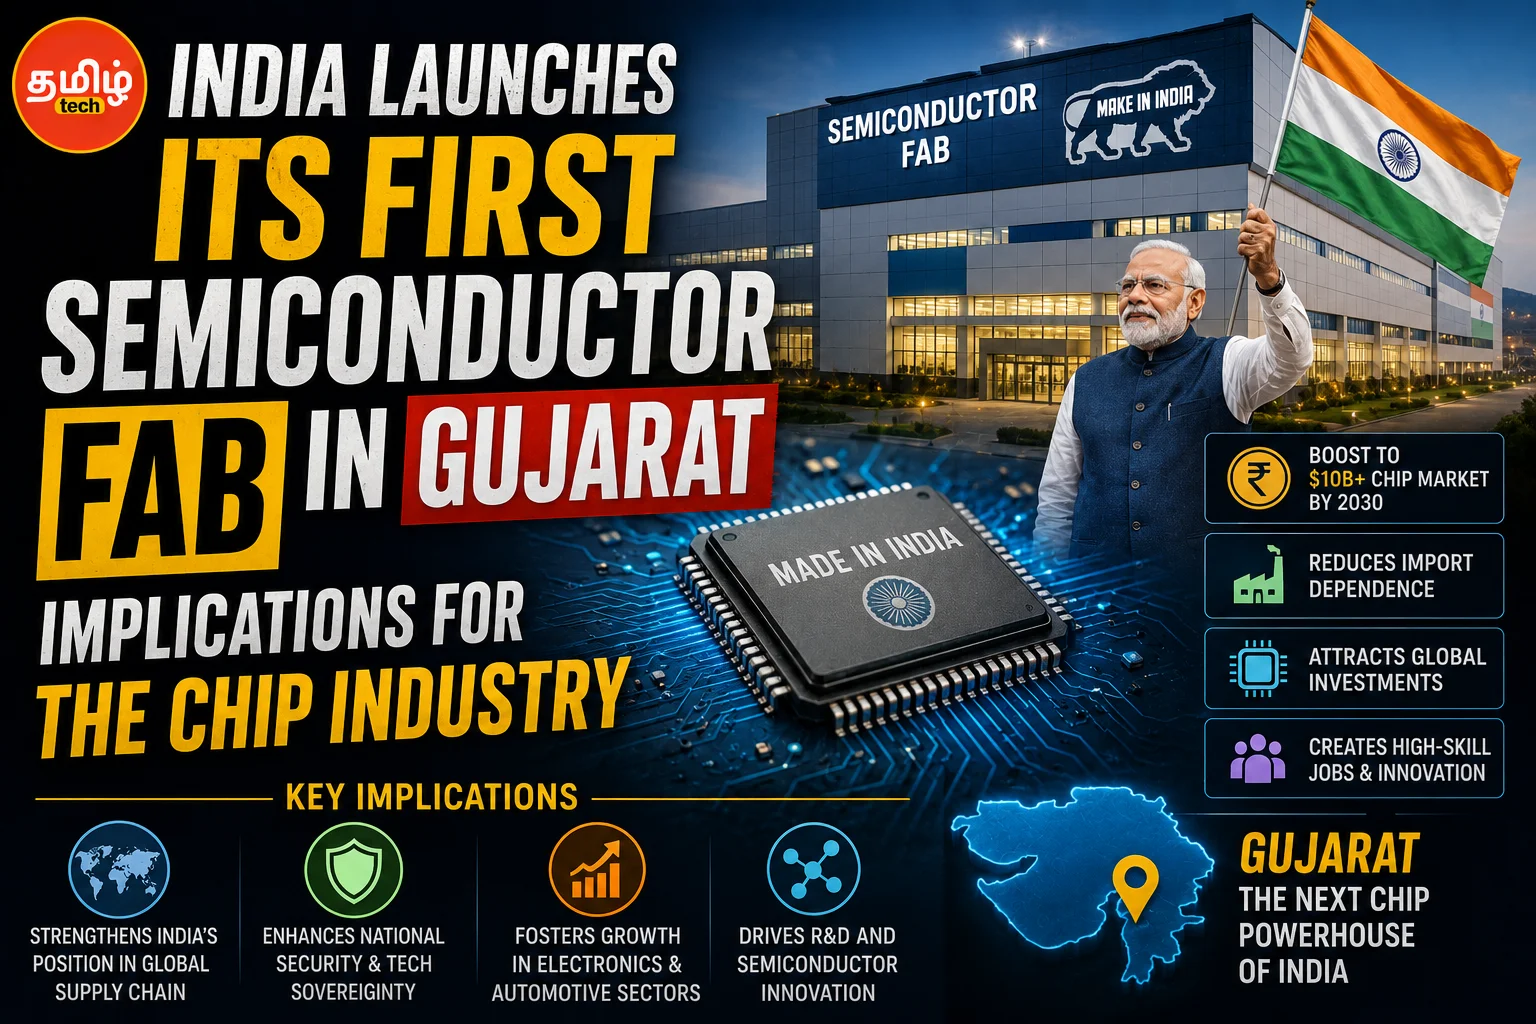
India’s semiconductor mission has officially launched its first fabrication plant in Gujarat, targeting a 28‑nanometer node by 2027 with an estimated investment of close to ten billion US dollars. The fab is expected to produce around fifty thousand wafers per month, serving domestic smartphone, automotive and industrial chip demand.
This move aims to cut the country’s reliance on imported semiconductors, create over fifteen thousand direct and indirect jobs, and position India as a credible alternative in the global chip supply chain. Success will depend on securing skilled talent, reliable power and water supplies, and continued policy support.
Opening Hook + What’s the News
After years of chip shortages that stalled everything from smartphones to cars, India has taken a decisive step toward self‑reliance. The government‑backed India Semiconductor Mission announced that the first fab, located in the Dholera Special Investment Region of Gujarat, will start pilot production in late 2026.
The facility, a joint venture between the Indian government, a consortium of domestic conglomerates and a foreign technology partner, will focus on the mature 28‑nanometer process node. Initial capacity is set at fifty thousand wafers per month, with plans to expand to advanced nodes later in the decade.
Background / History / How We Got Here
India’s push for domestic chip making began in earnest with the 2021 Production Linked Incentive (PLI) scheme for semiconductors and display manufacturing. Early attempts to attract global foundries stalled over land, water and talent concerns, prompting a shift toward a government‑led fab.
Over the past two years, the mission has secured land parcels, cleared environmental clearances and signed technology transfer agreements. The Gujarat fab is the first concrete outcome of this strategy, marking a shift from pure fabless design to actual silicon production.
Full Details — Specs, Numbers, How It Actually Works
The fab will use 28‑nanometer lithography tools from a leading European supplier, capable of producing logic chips, power management ICs and analog components. Wafer size is 300 mm, with a target yield of over sixty percent after ramp‑up.
Total capital expenditure is estimated at US 9.8 billion, split roughly 40 % equity from the government consortium, 30 % debt financing and 30 % from the technology partner. The plant will consume about 120 megawatts of power and 1.2 million cubic metres of water annually, sourced from dedicated renewable‑power contracts and a recycled water plant.
India Impact — INR Pricing, Availability, Who It’s For
Locally produced 28‑nm chips are expected to reduce the landed cost of smartphone system‑on‑chips by roughly eight to ten percent, translating to savings of roughly ₹150‑200 per device at retail. Automotive ECUs and industrial motor drives could see similar cost benefits.
Availability is slated for early 2027 for pilot runs, with volume shipments expected mid‑2028. The primary customers will be Indian OEMs in mobile, consumer electronics, automotive and industrial sectors, with excess capacity offered to global fabless firms seeking a diversified supply base.
Real‑World Use Cases / Step‑by‑Step How‑To
Consider a smartphone SoC design: an Indian fabless company completes the RTL design, runs simulations, then sends the GDSII file to the Gujarat fab. The fab performs photolithography, etching, deposition and testing steps over a four‑week cycle, delivering tested die ready for packaging.
For an automotive ECU, the process is similar but includes additional high‑temperature burn‑in and automotive‑grade testing. Once packaged, the chips are sent to local assembly lines, reducing lead time from overseas shipment from eight weeks to under two weeks.
Comparison / Alternatives — Pros & Cons
Compared with importing 28‑nm wafers from Taiwan’s TSMC or South Korea’s Samsung, the Gujarat fab offers lower logistics costs, immunity from geopolitical tariffs and eligibility for PLI incentives. However, the per‑wafer cost is currently estimated to be 10‑15 % higher due to nascent ecosystem and higher financing costs.
Alternatives include staying fabless and outsourcing to existing overseas fabs, or investing in older 45‑nm/65‑nm nodes locally for less complex chips. Each path trades off capital intensity, time‑to‑market and technology node suitability.
TamilTech’s Honest Take + What to Expect Next
The Gujarat fab is an ambitious leap that could reshape India’s electronics landscape, but success hinges on solving the talent gap and securing uninterrupted utilities. Early yields will be critical; any delay could erode the cost advantage.
Look for the first pilot wafer run in late 2026, volume production by mid‑2028, and possible expansion to 14‑nm or FinFET nodes by 2030 if the initial phase meets yield and cost targets. Continued policy support and skilled‑worker pipelines will decide whether this becomes a cornerstone of India’s tech ambition.


Comments (0)
Be the first to comment!