


Key Takeaways
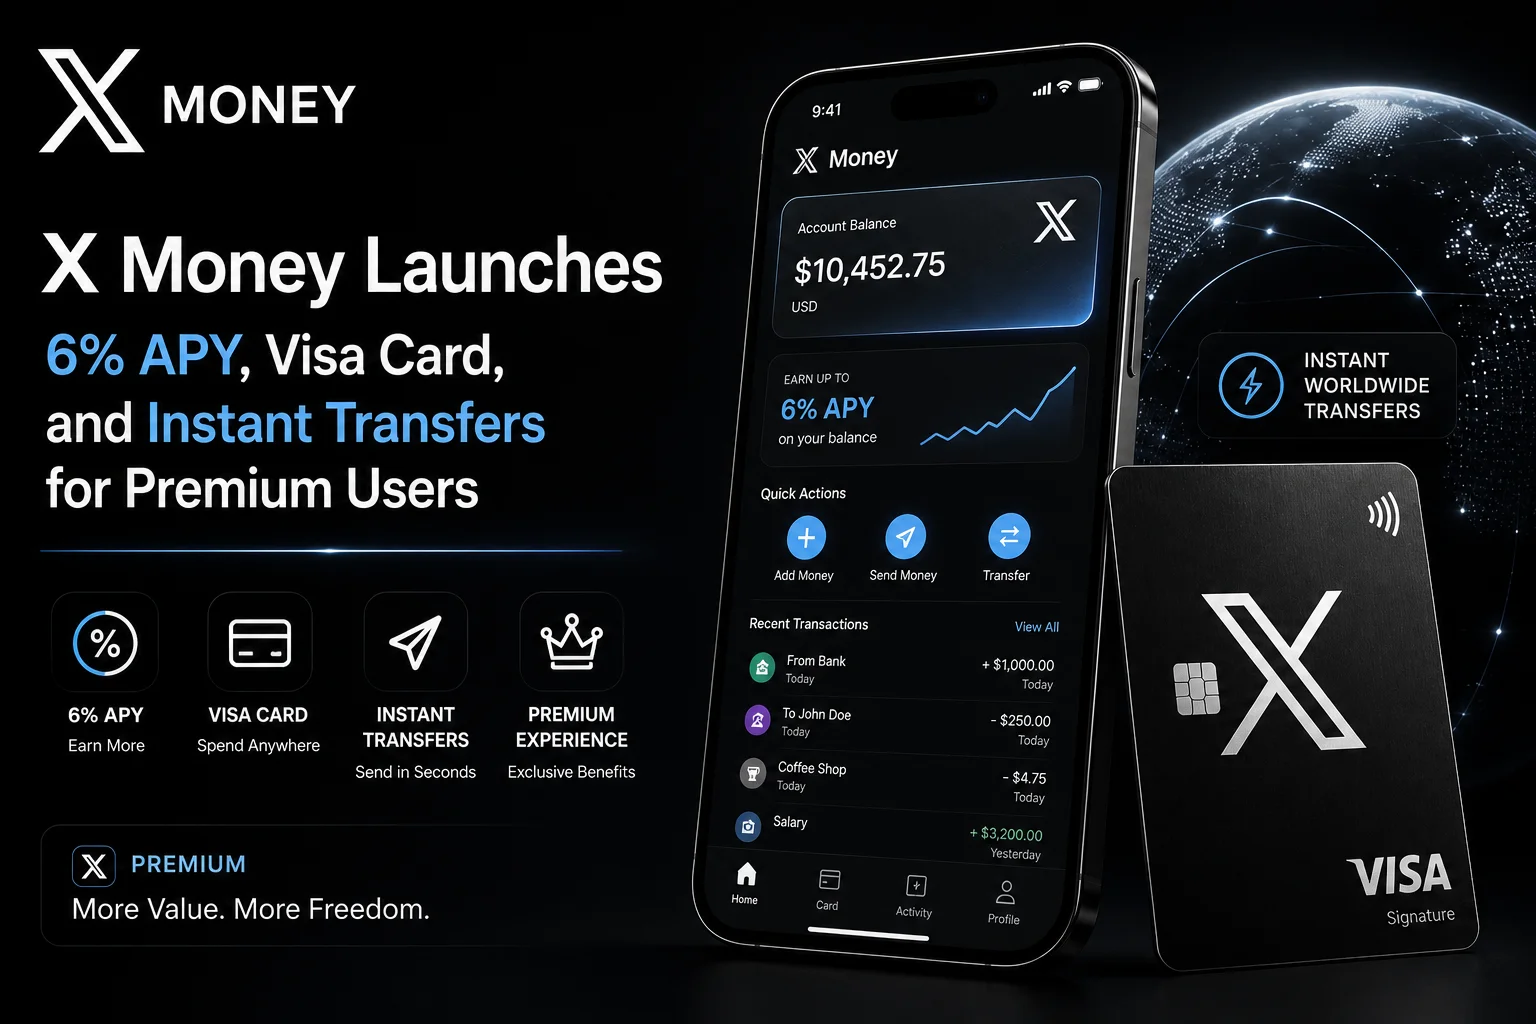
- X Money offers a massive 6% APY on deposit accounts, significantly higher than most traditional US savings accounts.
- The service includes a physical and virtual Visa debit card for seamless offline and online spending.
- Initial rollout is exclusive to X Premium and Premium+ subscribers based in the United States.
- Instant peer-to-peer (P2P) transfers are now available directly within the X chat interface with zero fees.
- While not yet in India, X is reportedly in talks for a potential UPI-linked partnership for a 2027 release.
The Everything App Vision is Finally a Reality
So, here's the thing—Elon Musk has been talking about turning X into an 'Everything App' since he took over the platform, and today, in July 2026, it’s actually happening. X Money has officially started rolling out to users in the US. This isn't just some small digital wallet update; this is a full-blown financial ecosystem integrated right into your social media feed. If you are a Premium or Premium+ subscriber, your X profile is now essentially a bank account. I've been tracking the beta tests for months, and the final version looks much more polished than I expected.
Why is this a big deal? Because X isn't just competing with Facebook or Threads anymore; they are going straight after the likes of JP Morgan, Chase, and even fintech giants like Revolut and Monzo. By combining your social identity with your financial identity, Musk is betting that you'll never want to leave the app. Imagine scrolling through your timeline, seeing a product you like, and buying it instantly using your X balance, or tipping a creator without ever needing a third-party gateway like PayPal or Stripe. It’s seamless, but it also raises a lot of questions about how much data we want one company to have.
How X Money Works: 6% APY and the Visa Card
Let's talk numbers because that’s what really matters here. X Money is offering an eye-watering 6% APY (Annual Percentage Yield) on your deposits. For context, most traditional banks in the US are still hovering around 0.01% to 0.50%, and even high-yield savings accounts are struggling to stay above 4.5% in 2026. By offering 6%, X is basically buying its way into your pocket. They want your paycheck to be direct-deposited into X Money. It’s a bold move, and honestly, for anyone looking to grow their idle cash, it’s a very tempting offer. But remember, this is currently locked behind the Premium paywall, so you have to factor in that subscription cost.
Then there’s the hardware. X is shipping out physical Visa debit cards to its users. These aren't just plain plastic cards; they feature a minimalist design with your X handle engraved on them. You can use this card anywhere Visa is accepted—grocery stores, gas stations, or international travel. The app gives you instant notifications for every swipe, and you can freeze the card with one tap if you lose it. The integration is tight; your 'Payments' tab in the X app now looks like a high-end banking dashboard with spending analytics, categorized expenses, and even a 'Goals' feature to help you save for that next Tesla or Starlink kit.
Instant Transfers: Goodbye Venmo?
One of the coolest features I’ve tested in the early access is the P2P transfer system. We’ve had 'Tips' on X for a while, but this is different. You can now send money to any other X Money user as easily as sending a DM. There are no fees, and the transfer is truly instant. In my experience, it’s even faster than Venmo or Cash App because it doesn't require a separate app launch or a multi-step verification process once you're logged into X. You just hit the '+' icon in a chat, enter the amount, and it's gone.
For creators, this is a game-changer. If you're a journalist, artist, or influencer on X, you can get paid directly by your followers, and that money is immediately available on your X Visa card. No more waiting 3-5 business days for a payout to hit your local bank. This creates a closed-loop economy where money circulates within the platform. However, the catch is that both the sender and the receiver currently need to be Premium subscribers in the US, which limits the reach for now. I expect them to open this up to free users eventually, perhaps with a small transaction fee.
The India Context: When is it coming to us?
Now, I know what you’re thinking—what about India? As of July 2026, X Money is US-only. But don't lose hope just yet. My sources indicate that X has been in active discussions with the RBI (Reserve Bank of India) and NPCI. India is the world leader in digital payments thanks to UPI, and Musk knows he can't ignore this market. However, India has very strict data localization laws. The RBI requires all payment data to be stored locally within India, which is a hurdle X is currently working to clear.
If and when X Money launches in India, it probably won't look exactly like the US version. We might see an 'X-UPI' integration where you can link your existing bank accounts to your X handle, similar to how Google Pay or PhonePe works. The 6% APY might also be hard to sustain here given our local banking regulations, but even a 5% rate would shake up the Indian banking sector. For now, Indian users can only look at the US rollout as a preview of what’s coming. If you're a creator in India, you'll still have to rely on the existing ad-revenue sharing model which pays out via Stripe.
Is it Safe? Privacy and Security Concerns
This is where things get a bit controversial. Do you trust X with your life savings? We’ve seen the platform go through a lot of changes and some technical glitches over the last few years. Moving from a social network to a bank requires a massive shift in security infrastructure. X claims they are using bank-grade encryption and are partnered with FDIC-insured banks in the US to protect user deposits up to $250,000. This means even if X as a company faces trouble, your money is technically held by a regulated financial institution.
But then there's the privacy aspect. X already knows what you tweet, who you follow, and what you like. Now, they will also know exactly where you spend your money, how much you earn, and what your financial habits are. That is a goldmine of data for advertisers. While X says they won't sell your transaction data, the fine print often allows for 'internal use to improve services.' If you're someone who values privacy above all else, X Money might feel a bit too much like 'Big Brother' is watching your wallet.
TamilTech’s Honest Take: Should You Switch?
So, what do we think at TamilTech? Look, the 6% APY is a massive hook. If you are already paying for X Premium, it’s almost a no-brainer to move some of your savings there just for the interest. The convenience of a Visa card that’s tied to your social profile is also pretty cool for the tech-savvy crowd. It’s the ultimate flex for Musk fans. But for the average user, I’d say wait and watch. Banking is about trust, and X still has to prove it can handle the responsibility of being a financial guardian.
In the long run, this move could either make X the most powerful app on the planet or it could be a massive overreach that alienates users. For us in India, the wait continues. But one thing is for sure—the days of social media being just about 'likes' and 'retweets' are officially over. Your timeline is now your bank branch. Let's see if other platforms like Instagram or LinkedIn try to follow suit, though I doubt anyone can be as aggressive as Musk with that 6% interest rate. Stay tuned, because as soon as there's a hint of an India launch, you'll hear it here first!





Comments (0)
Be the first to comment!